For most of the past decade, the question of who would issue the digital money of the future felt theoretical. It is not theoretical any more. Two models are now competing openly for the same payment flows, and they represent fundamentally different answers to a question that predates blockchain entirely: should the base layer of money be a public utility or a private product operating under public rules? The answer emerging is not a clean victory for either side, but a geographic split that increasingly maps onto broader divisions in the world economy.
Two forms of digital money that are easy to confuse
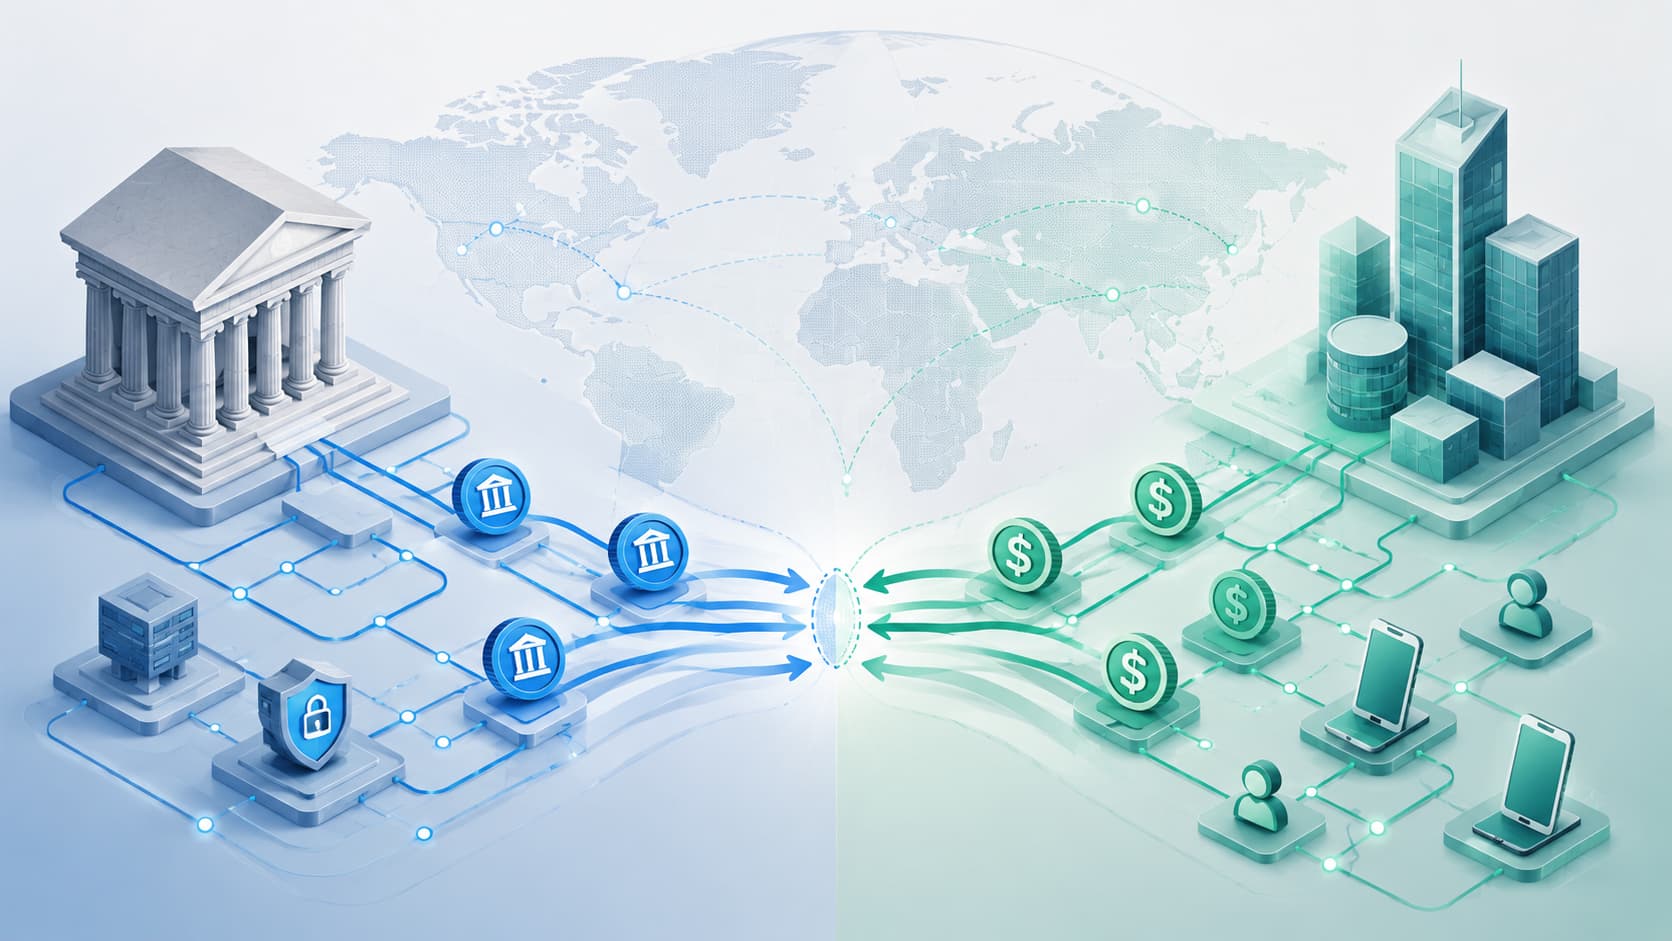
The distinction matters more than the shared vocabulary suggests. A central bank digital currency is a direct liability of the central bank, issued either to the public in retail form or to financial institutions in wholesale form. It is base money in digital dress. A stablecoin is issued by a private company and backed by reserve assets, which means its holder is a creditor of that company rather than of the state. The difference sounds academic until a moment of stress arrives, at which point it becomes the only thing that matters.
That difference is precisely why central banks began the work at all. The digital currency project was, from the beginning, the traditional financial system’s response to the rapid growth of privately issued digital dollars. Central banks watched a parallel settlement layer form outside their perimeter and concluded they needed an answer of their own. What none of them fully anticipated was how fast the private side would scale once regulators granted it legal certainty.
The scale the private side has reached
The numbers now describe an established payments industry rather than a crypto curiosity. Total stablecoin market capitalization has been hovering above three hundred billion dollars, having climbed from roughly two hundred and eight billion at the close of the prior year. The category added seventy-five billion in one year and over a hundred billion in the next. Tether remains the liquidity heavyweight at around a hundred and eighty-four billion, while Circle’s dollar token reached seventy-eight billion on the strength of its positioning as the compliance-first option for American institutions.
Transaction volume tells the more consequential story. Annual stablecoin transfer volumes have surpassed the yearly throughput of Visa and Mastercard combined, and in a single recent month these networks moved over ten trillion dollars. Remittance platforms, payroll providers and payment service processors now hold and move these instruments as part of routine operations. That is the crucial shift: balances held as working capital are durable in a way speculative balances never were. Every business that keeps operating funds in tokenized dollars adds supply that does not evaporate when trading sentiment turns.
One structural fact frames everything else. Roughly ninety-seven percent of all stablecoin market capitalization is denominated in US dollars. Whatever else this technology does, it currently exports dollar exposure into every jurisdiction that adopts it.
Washington chose the private path and closed the public one
American policy resolved the question with unusual bluntness. Federal stablecoin legislation established the first national framework for payment tokens, requiring dollar-for-dollar reserves and restricting issuance to licensed entities. Supply grew fifty percent in the calendar year it passed. For corporate boards that had treated the asset class as a legal grey zone, the calculus changed overnight.
The same statute contains a provision that determined the other half of the outcome: an explicit prohibition on the Federal Reserve issuing a retail digital currency to the public. The central bank retains authority to research wholesale concepts, but a digital dollar that ordinary Americans could hold is off the table by law, reinforced by an executive order banning work on a dollar-denominated central bank currency. The policy effect has been to channel all digital-dollar demand toward regulated private issuers.
The law also bars issuers from paying interest on their tokens, though a workaround persists. Dollar tokens can still earn as much as three and a half percent through arrangements structured as rewards, roughly seventy times what comparable Chinese deposits yield. Closing that loophole has become the top policy priority for American banks, who fear deposit flight for exactly the same reason Chinese authorities once feared it.
Europe is attempting both tracks at once
The European response has been notably more anxious, driven by a concern that dollar-denominated tokens could effectively dollarize European payment infrastructure. Brussels is pursuing three parallel tracks: regulation through its markets-in-crypto-assets framework, encouragement of euro-denominated private tokens, and a public infrastructure project in the form of a digital euro now moving toward an issuance decision.
Private-sector movement has been real. Ten major European financial institutions, including ING, KBC, Danske Bank, UniCredit, SEB, CaixaBank and Raiffeisen Bank International, formed a joint venture to develop a compliant euro token, with BBVA and Bancomat announcing separate plans. The obvious risk is fragmentation, which would undercut the goal of a unified pan-European payments ecosystem before it exists.
For operators, the transatlantic reality is expensive. There is no mutual-recognition or equivalence arrangement between the American and European frameworks. A token authorized in one has no standing in the other, which forces any issuer with ambitions on both sides to run two compliance programmes in parallel, with separate licences, separate reserve pools, separate auditors and regulators who will never defer to one another.
China took the opposite road and then hesitated
Beijing pursued the mirror-image strategy: banning foreign crypto assets including private stablecoins while promoting its state-issued digital yuan, which has crossed sixteen trillion yuan in cumulative transactions. Yet the enthusiasm has cooled. Authorities scaled back a planned experiment permitting stablecoins in Hong Kong, and the domestic retail currency has struggled with the problem that defeats nearly every such project. Launching a central bank currency is technically achievable. Persuading citizens and merchants to abandon incumbent payment rails is the genuinely hard part.
That pattern is the recurring lesson. Outside China, no retail central bank currency has come close to the scale of major payment stablecoins, even though a hundred and thirty-four countries representing ninety-eight percent of global output are exploring one in some form, up from thirty-five a few years ago.
Where the public model is actually winning
The retail side is not where central banks are succeeding, and the more interesting activity has moved to wholesale. Wholesale currencies operate behind the scenes, letting banks settle with one another instantly using tokenized central bank money. They attract none of the surveillance objections that have dogged retail proposals, because ordinary citizens never touch them.
Project Agorá, involving the New York Federal Reserve alongside the Bank of Japan and the Bank of France, is the most ambitious of these efforts. On the other side of the geopolitical divide, the mBridge multi-currency project involving China, Hong Kong, Thailand, the United Arab Emirates and Saudi Arabia points toward cross-border settlement channels less dependent on Western-controlled infrastructure. Neither is a systemic alternative to existing arrangements yet, but both indicate where public digital money has found genuine product-market fit.
What is actually being decided
Beneath the technical vocabulary, this is a contest over the future of cross-border payments and currency competitiveness. India’s central bank has argued that public digital currencies preserve the singleness of money and should remain the ultimate settlement asset and anchor of trust, warning that private tokens open new channels for instability during periods of market stress. The counterargument is equally serious: retail public currencies raise real privacy concerns and could destabilize commercial banking by turning citizens into direct customers of the central bank.
The likely outcome is neither displacement nor coexistence in equal measure, but a layered arrangement in which private tokens dominate retail and commercial flows under public rules, while central banks retain the settlement layer beneath them. That is a smaller role than monetary authorities once imagined for themselves, and a larger one than the technology’s early advocates ever intended to leave them.